Search the research desk.
Type a market, company or commodity and jump straight into the K2 report that covers it.
K2 Capital is a Hong Kong-based investment firm and a trusted channel to East and Southeast Asian investments, delivering disciplined strategies and customized portfolio solutions.
Opportunity moves across borders. K2 Capital, a trusted channel into East and Southeast Asian investments.
K2 Capital Limited · Hong Kong, China
[ What we do ]
From equities and natural gas to venture capital and franchising, across Mainland China, Hong Kong and Southeast Asia.
Read the research[ Portfolio ]
Funds, ventures and an institute across asset management, artificial intelligence, F&B and education.
Equity, commodity and thematic research from the K2 research team, on markets across Asia and beyond. Selected reports are open to everyone; clients get full access to every report.
Type a market, company or commodity and jump straight into the K2 report that covers it.
Partnerships, advisors, funds and portfolio news from K2 Capital and its companies.
Clients & recognition
[ Portfolio ]
From franchise licensing and F&B ventures to fund raises and AI acquisitions. Hover a row for a preview, select it to read the release.
[ Global Research ]
by K2 Capital Management
Gateway to strategic investment insights across Asia and beyond. Become a client to gain full access to every report.
[ News & Insights ]
by K2 Capital Management
Stay up to date with our latest news and insights.
[ Aether portfolio ]
[ Accelerators, partners and competitions ]
Press releases featuring Oliver Tedja and the firms he co-founded.
K2 Capital is advised by leaders from listed companies in China and from global financial services.
[ Contact ]
K2 Capital Limited, Hong Kong. Tell us what you are working on and the right person will get back to you.
Commodities
China’s steel production is projected to remain below its 2020 peak as the property slowdown, decarbonisation goals, and tighter credit policies weigh on construction.
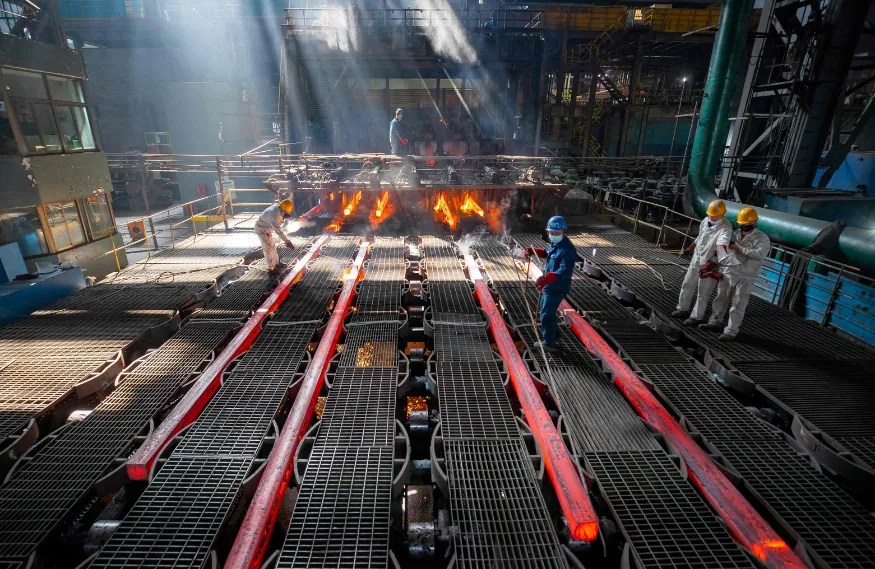
China’s crude steel output in 2025 has softened relative to 2023–24 peaks, with rolling monthly declines through mid-2025; nonetheless, iron-ore imports and port inventories have remained resilient, a divergence that signals stockbuilding, tactical procurement, or timing lags between raw-material purchases and mill throughput. ( Worldsteel )
State and industry policy aim to prune inefficient capacity and curb new capacity additions in 2025–26; this policy stance supports a structurally lower domestic steel production trajectory over the medium term, which is a negative demand signal for seaborne iron ore versus the boom years. ( Reuters )
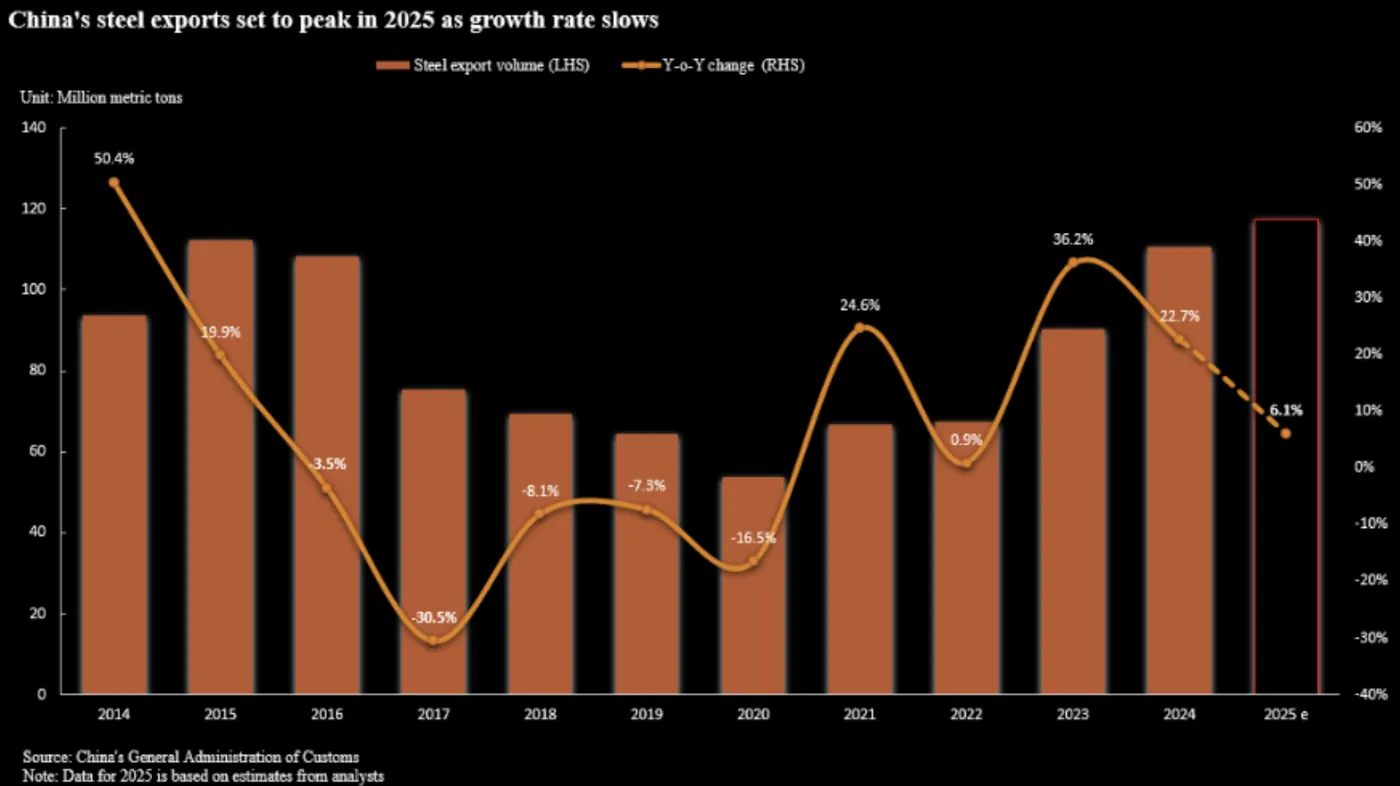
Despite weaker domestic demand, China’s steel exports are elevated (near/above 100 Mt in 2025), partially offsetting domestic weakness and supporting continued iron-ore imports for export-oriented mills. This export buffer complicates simple demand forecasts. ( Reuters Reuters )
Geopolitical / procurement dynamics introduce demand re-routing and price negotiation risk for miners and trading houses; the market may re-price counterparty and regional exposure if such measures persist. ( Reuters Reuters )
Net Implication: Under a base case – continued property weakness but limited stimulus plus elevated exports – iron-ore demand into China for 2025 is likely to be modest to slightly down y/y versus peak years, while price volatility will be driven by inventory swings, trade negotiations, and supply plans from major miners. ( Reuters Reuters )
Capacity/ Production Controls: Central and industry guidance in 2025 prioritises pruning inefficient blast-furnance steel capacity and strictly curbing new capacity additions,, with measures described as spanning 2025-2026. The objective is to reduce overcapacity and improve sector efficiency. This reduces the long-run baseline for domestic crude steel output. ( Reuters )
Procurement & State Influence: State-linked procurement bodies such as China Mineral Resources Group (CMRG) have increased bargaining power in iron-ore purchasing and long-term contract negotiation, and there were reported directives in late-Sep/Oct 2025 advising mills to pause purchases from specific suppliers. That dynamic can reshape counterparty risk and cause short-term re-routing of seaborne flows. ( Reuters Reuters )
Export-oriented Strategy: in the face of weak domestic demand, major mills (e.g., Baosteel) are explicitly targeting higher export volumes – a policy/operational adaptation that preserves mill throughput and therefore sustains some ore demand despite domestic consumption declines. ( Reuters )
Environmental/ Decarbonization Pressure: Ongoing policy momentum to reduce emissions and force exit of inefficient capacity could accelerate the share shift from BF-BOF toward EAF/ higher-scrap routes over time-reducing ore intensity per tonne of crude steel. While impactful medium-term, the transition pace in 2025 is incremental. ( Reuters )
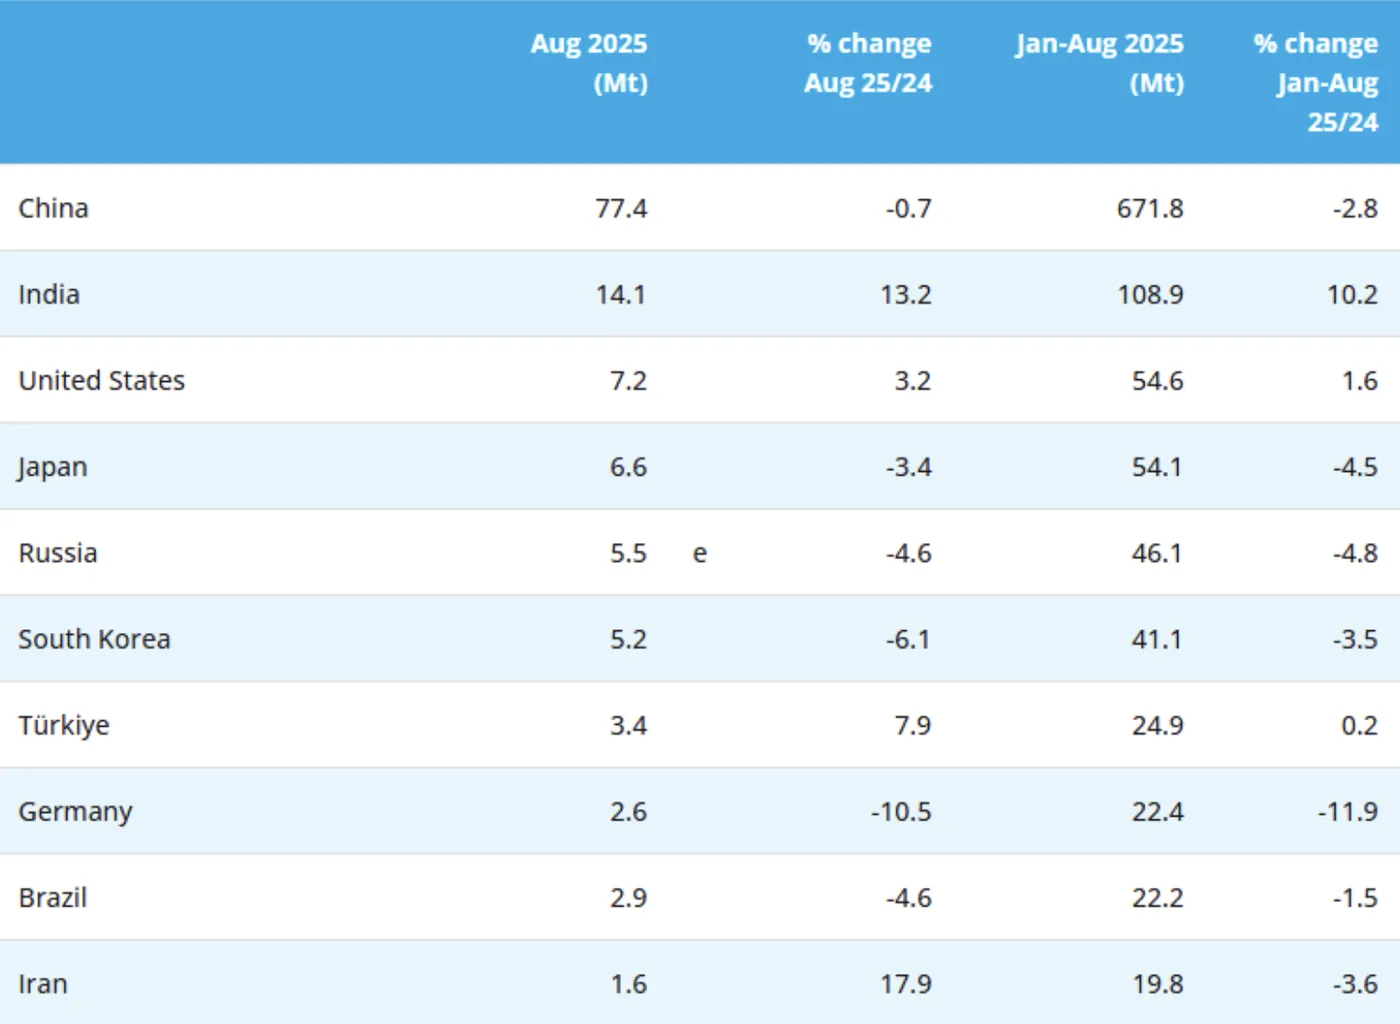
China remains the world’s largest crude steel producer, but monthly production in 2025 has shown softening: August 2025 crude steel output stood at ~77.4 Mt (down y/y), and several monthly series through mid-2025 showed declines from 2024 levels. These patterns reflect weak construction activity, manufacturing softness and capacity rationalization.
Construction & real-estate: Primary demand channel and the dominant swing factor. Real estate weakness has been the primary domestic headwind into 2024–25. ( Reuters )
Manufacturing & autos: Moderately weak but more heterogeneous by subsector. Recovery here would lend upside to steel consumption. ( Reuters )
Exports: Record-level exports (near/above 100 Mt in 2025) have acted as a partial offset to weaker domestic consumption, sustaining mill utilization and ore needs. ( Reuters Reuters )
Global seaborne iron-ore markets: China consumes ~75% of seaborne ore; shifts in Chinese demand directly alter global balances, prices and miners’ revenue outlooks. A sustained downshift in Chinese steel output materially lowers global seaborne consumption. ( Reuters Worldsteel )
Pricing & miners’ strategy: Major miners (BHP, Rio, Vale, FMG) base investment and contractual decisions on China’s demand signal; unexpected policy actions (e.g., procurement restrictions) can force contract renegotiations, re-routing and short-term price dislocations. ( Reuters BHP )
Trade & geopolitics: Export surges from China can depress global steel prices and provoke protectionist responses (tariffs/anti-dumping), which in turn affect global commodity and manufacturing value chains. ( Reuters )
Tension between supporting employment/real-economy (via stimulus) and structural overcapacity/emissions reduction will shape the policy mix and thus the steel-ore trajectory. ( Reuters )
Become a client to gain full access to every K2 report.
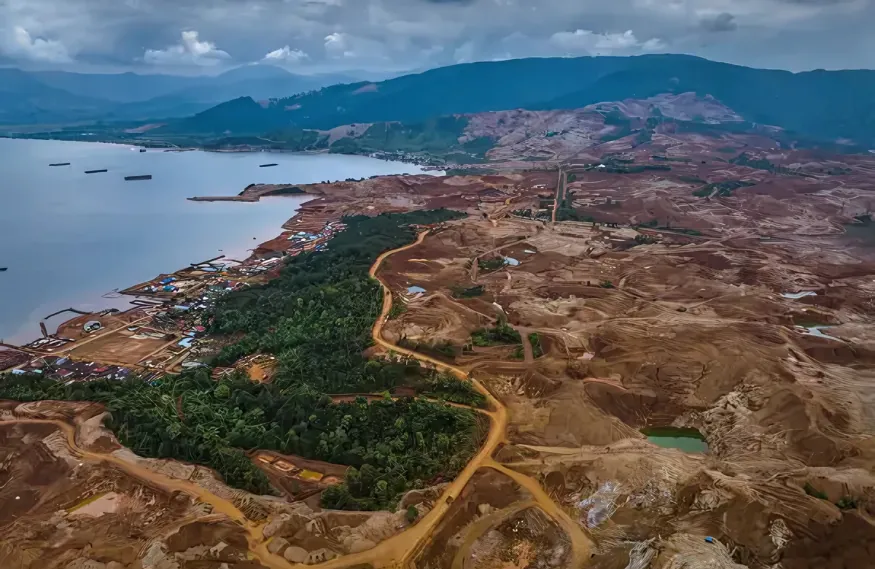
How Jakarta’s resource nationalism is reshaping EV supply chains, LME pricing and the geopolitics of critical minerals, and where capital should be positioned.
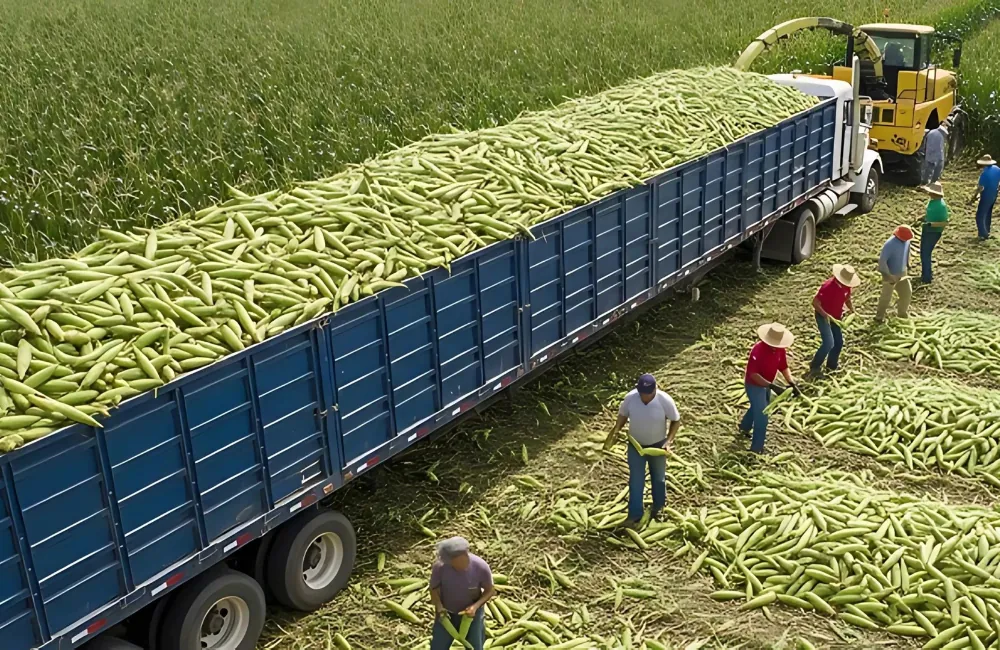
Brazil’s safrinha corn season, the second crop planted after soybeans are harvested, is the defining variable for global corn supply balances through the second half of 2026.
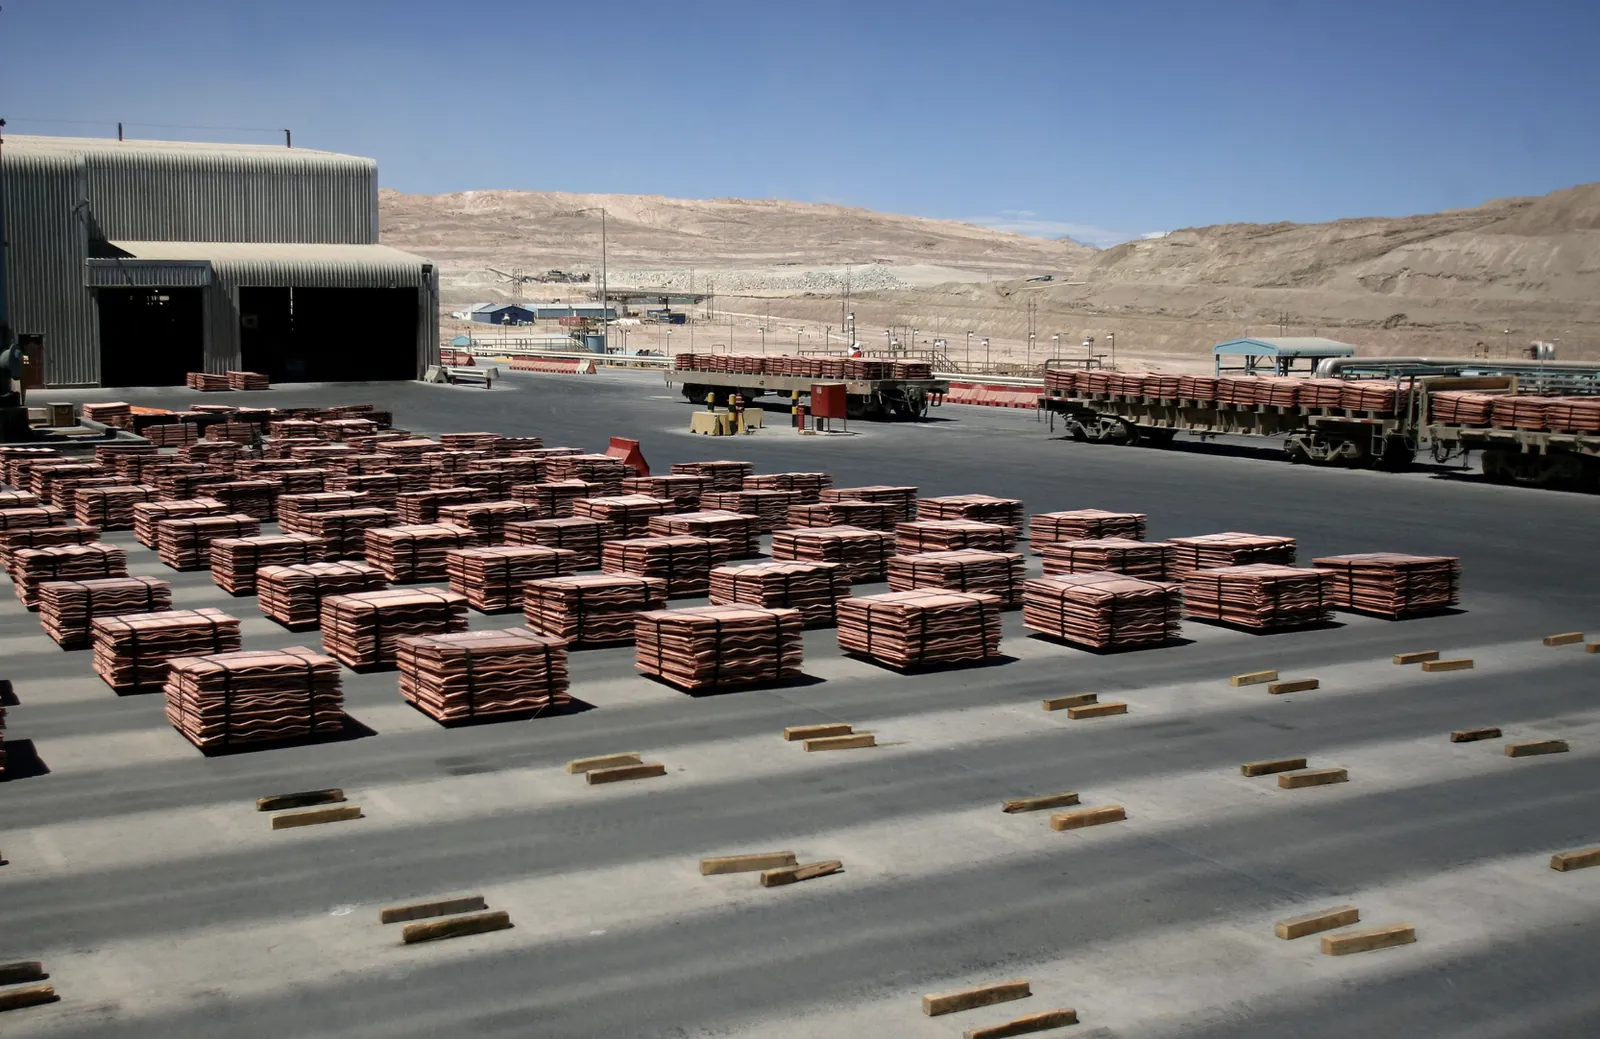
Peru and Chile, together responsible for about 40% of global mined copper output, saw a wave of production losses in 2025 that helped turn the 2026 outlook from surplus to deficit.